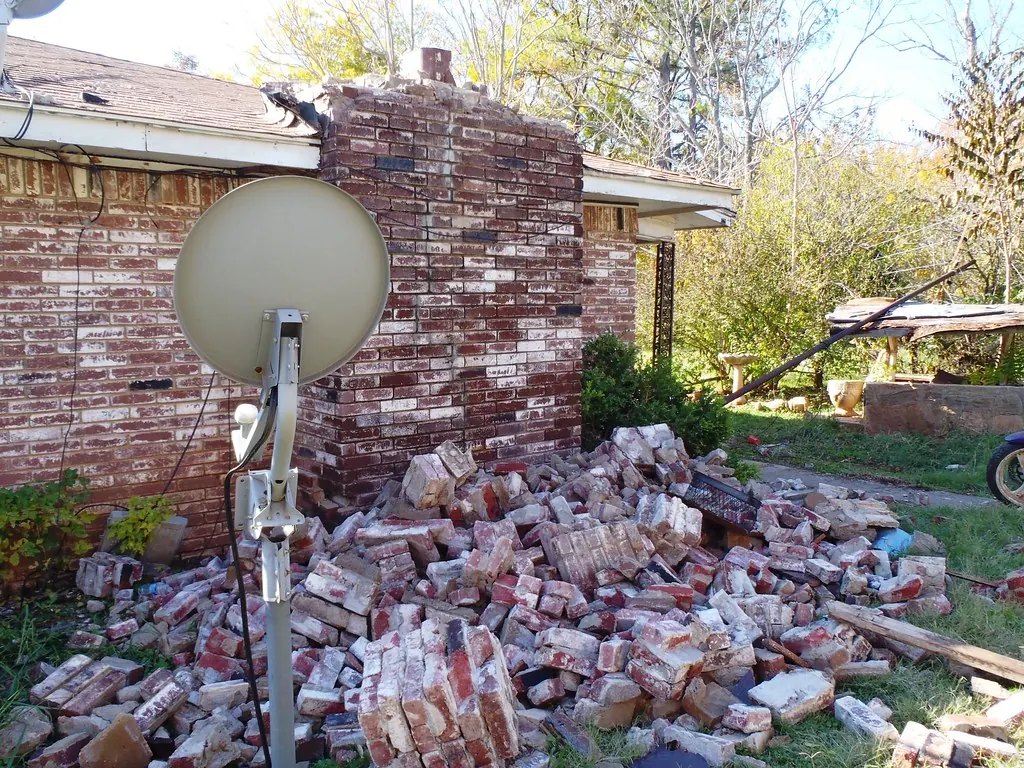
California’s earthquake history, from Loma Prieta in 1989 to Northridge in 1994 and Ridgecrest in 2019, has shaped how insurance handles quake-related losses. The key point: earthquake damage and fire following an earthquake are treated differently.
Earthquake damage is usually excluded
Standard homeowner policies exclude earth movement, including earthquakes. Coverage for shaking damage requires a separate earthquake policy, such as one from the California Earthquake Authority or a private insurer, with its own percentage deductible.
Fire following is usually covered
If an earthquake causes a fire, the resulting fire damage is generally covered under the standard fire coverage of a homeowner policy. That’s a long-standing feature of California’s standard fire policy.
When both happen
A home might be cracked by shaking and then damaged by fire. The earthquake policy responds to the shaking damage, after its deductible, and the homeowner policy responds to the fire damage. Separating the two scopes carefully is essential.
What to do
- Document shaking damage before any fire damage, if possible.
- Report to both insurers.
- Keep separate estimates for each peril.
See how much an earthquake deductible could cost you with our earthquake deductible calculator.