California’s rivers in the sky
Atmospheric rivers are long plumes of Pacific moisture that deliver much of California’s annual precipitation. The winter of 2022–23 brought a string of them, flooding parts of Sacramento, Santa Cruz, Monterey and Ventura counties and toppling trees across the Bay Area. A February 2024 storm hit Los Angeles with record rain, and January 2024 flooding struck neighborhoods in San Diego. In 2017 the damaged Oroville Dam spillway forced evacuations downstream in Butte County.
Covered water versus flood
Homeowner policies generally exclude flood, meaning surface water from rising rivers or overland flow, unless you carry separate flood insurance. But much storm damage is not flood:
- Rain entering through a roof or wall opening created by wind or a falling tree.
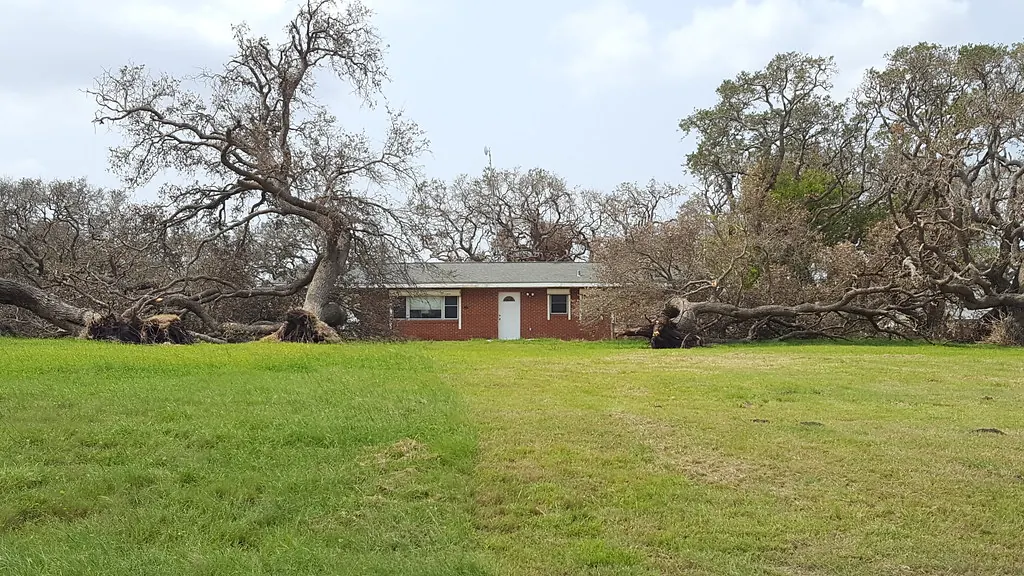
- Trees and limbs falling on the house, garage or fences.
- Sudden roof failures under heavy, saturated debris loads.
- Sewer backup, if your policy includes that endorsement.
Storm claim appraisal values the covered portion carefully, with clear documentation of where water entered and what it touched, so the covered loss is not diluted by an argument about flooding elsewhere on the property.
Mudflow and debris flows
Debris flows after wildfires, like the January 2018 Montecito disaster in Santa Barbara County, are typically treated under flood or earth movement exclusions in many homeowner forms. Some damage around those events may still be covered, such as a tree driven into a roof by wind. These claims need careful separation, and sometimes an attorney’s view on coverage.
What gets missed
- Drying and dehumidification beyond the first few days.
- Moisture mapping and removal of wet insulation and drywall.
- Mold remediation when drying was delayed by repeated storms. Many policies cap mold, so the limit matters.
- Exterior repairs to the roof and walls that let the water in.
Hurricanes rarely reach California, but Tropical Storm Hilary in August 2023 showed that remnants of Pacific storms can bring flooding rain and wind to the southern deserts and mountains. The same rain-versus-flood analysis applies.
Questions about atmospheric river & storm appraisal
My street flooded and my roof leaked. Is any of it covered?
Possibly. Roof leak damage is often covered even if flood damage from rising water isn’t. Documenting each separately is important.
Does appraisal work for storm claims?
Yes, when the carrier accepts some storm damage but disagrees on the amount. If it denies the whole claim as flood, that’s a coverage dispute.
How quickly should I dry out after a storm leak?
As soon as possible. Policies require reasonable steps to prevent further damage, and those costs are usually reimbursable.