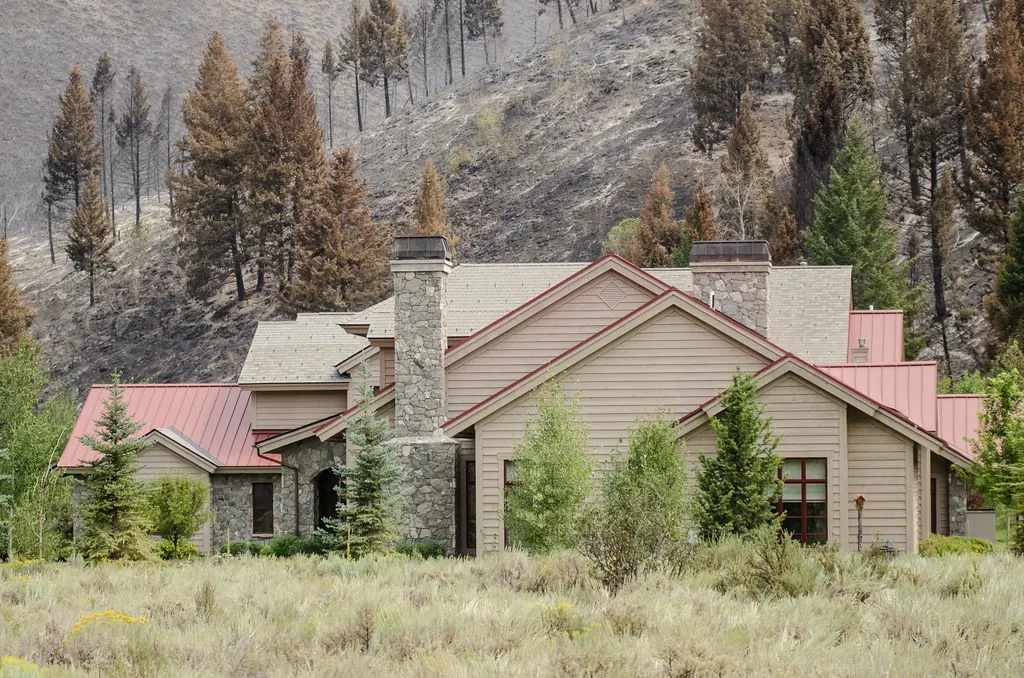
Partial fires and smoke
Kitchen fires, electrical fires and garage fires often damage only part of a house physically, but smoke and soot spread throughout. Wildfires add a different problem: fine ash and combustion particles that infiltrate even homes far from the flames, through attic vents, gaps and HVAC systems. Smoke damage claim appraisal values a scope that removes contamination rather than masks it.
Where smoke estimates fall short
- Testing: carriers may decline to pay for surface sampling or air testing. Without it, the scope tends to be minimal.
- HVAC: duct cleaning may not be enough for flex duct that has absorbed odor or particulates; replacement may be warranted.
- Insulation: attic insulation that captured ash may need removal and replacement rather than vacuuming.
- Repainting: cleaning walls without sealing and repainting often leaves odor that returns in hot weather.
- Contents: textiles, mattresses, upholstered furniture and porous items may not be restorable.
California’s wildfire smoke rules
After the 2025 Los Angeles fires, California regulators and the Legislature focused new attention on smoke claims, including how insurers test and clean homes affected by smoke. Requirements have been changing, so we check the current rules for your loss date before relying on them. Your policy language still controls the basic coverage.
Structural fires
For homes with fire damage to framing and finishes, we price demolition, structural repair, and rebuilding to current code, including the fire-resistant construction standards that apply in many wildland-urban interface areas. Building code upgrade coverage may pay for some of these costs; we identify which items trigger it.
Ask about ALE
If smoke makes the home unlivable while it is cleaned, additional living expenses may apply. The length of that period depends on a realistic cleaning and repair schedule, which we can help establish.
Questions about fire, smoke & ash claim appraisal
My house didn’t burn, but it smells of smoke. Is that a claim?
It can be. Smoke and ash damage from a nearby wildfire is commonly covered under homeowner policies when it causes physical damage.
Do I have to accept the carrier’s cleaning company?
Generally you can choose your own contractor, though the carrier may dispute its pricing. Appraisal can resolve the amount.
Can appraisal require testing?
Panels decide value. They can consider test results that either side provides, which is why getting independent testing early can help.