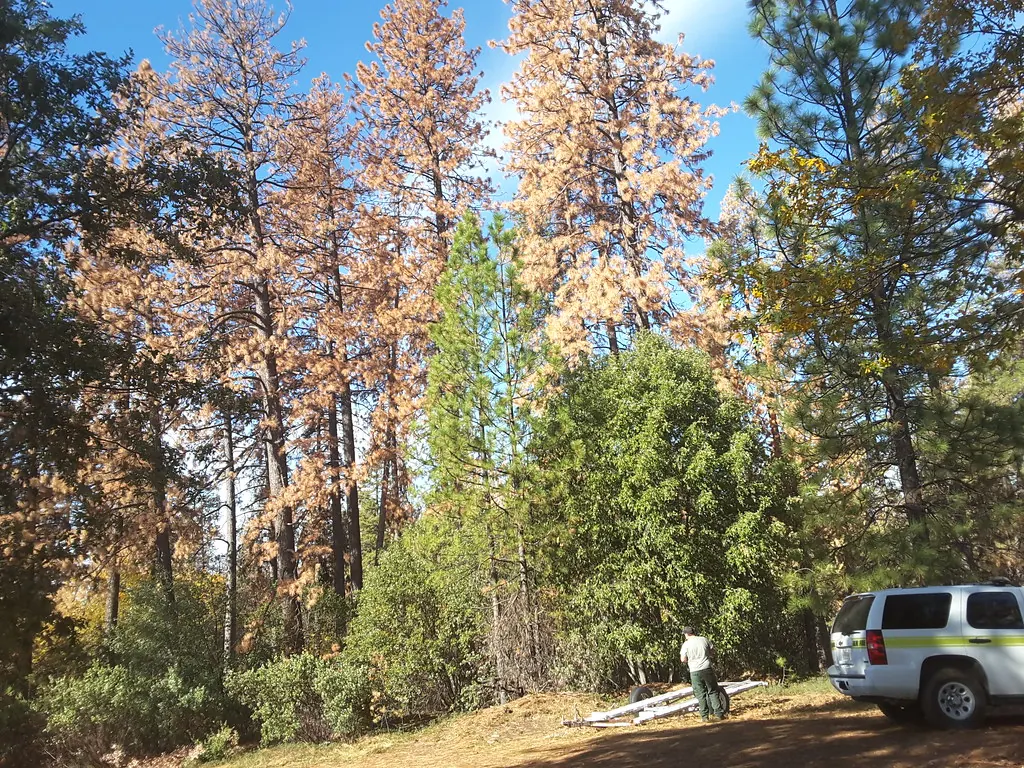
North Coast & Redwood Empire
Santa Rosa · Eureka · Ukiah
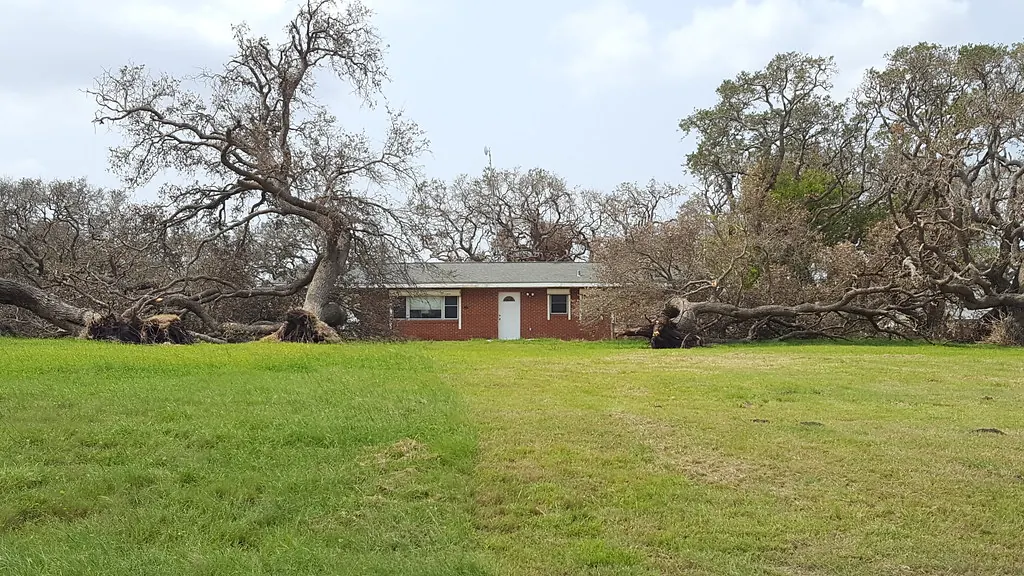
Wildfire, river flooding, falling redwoods and firs, and FAIR Plan policies on rural homes.
Independent appraisal · All 58 counties
Your carrier accepted the claim. The check still won’t rebuild the house, clean out the smoke or replace what you lost. California Insurance Appraiser prices the loss independently and takes it through the appraisal clause in your policy.
“Appraisal decides one thing: what the covered loss costs. That’s the only thing we do.”
The short version
Most short claims in California aren’t denied. They’re scoped narrowly. A tile roof priced as a spot repair, a smoke-filled house priced as a wipe-down, a hillside rebuild priced like a flat lot. California Insurance Appraiser exists for the space between “covered” and “paid in full.”
When you hire us, we become your appraiser under the policy’s appraisal clause, the process set out in the standard fire policy in Insurance Code §2071. We build the number from our own inspection, defend it line by line with the carrier’s appraiser, and present what remains to a neutral umpire.
Losses we value
12 services built around one job: a valuation of your loss that holds up in front of an umpire.
Service 01 Service 02
 Service 03
 Service 04
 Service 05
 Service 06
The California peril
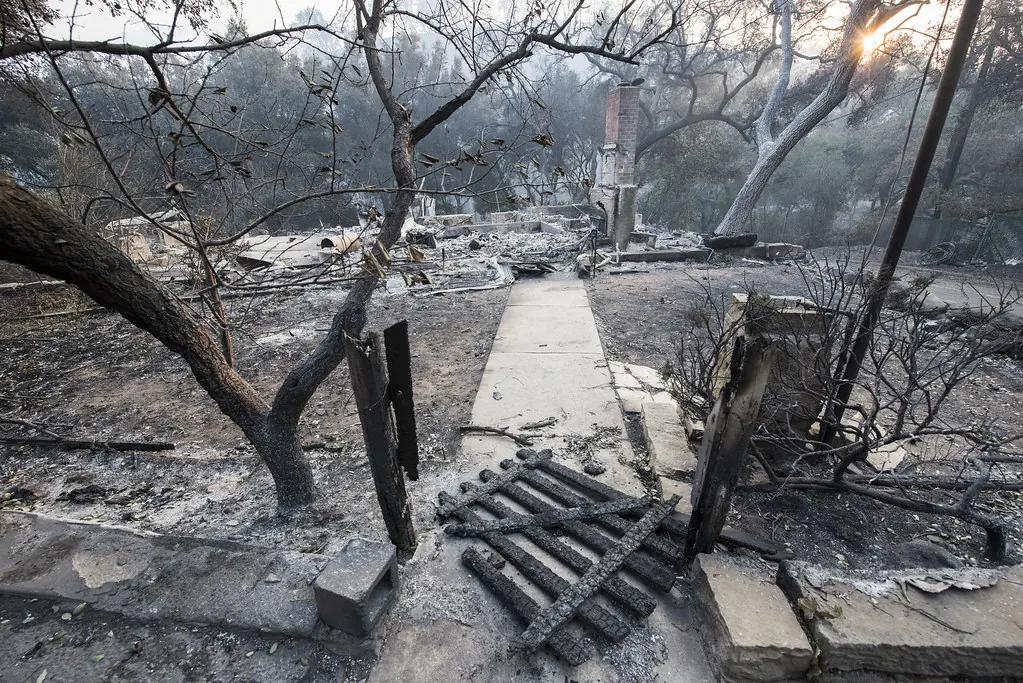
Tubbs, Camp, Woolsey, Palisades, Eaton. Each left thousands of families comparing a carrier’s rebuild figure with what local builders were actually charging. A California Insurance Appraiser can establish the full cost of a comparable rebuild under current code, which decides whether you reach extended replacement cost and code upgrade coverage.
The path
The appraisal clause turns an open-ended argument into a defined process. Here is how California Insurance Appraiser runs a file.
We read the policy, the carrier’s estimate and your photos, and tell you whether appraisal makes sense.
We inspect, measure and build our own line-item valuation, priced for your part of California.
Appraisal is demanded in writing and California Insurance Appraiser is named as your appraiser within 20 days.
We work through every disputed item with the carrier’s appraiser. Most gaps narrow here.
Remaining items go to the umpire. Any two signatures on an itemized award set the amount.
Two numbers
Enter the carrier’s estimate and your contractor’s. A large gap means a conversation with a California Insurance Appraiser is worth having; a small one usually closes faster with a documented supplement.
The full appraisal payoff estimator adds appraiser and umpire fees so you can see a realistic net figure.
Six regions
California Insurance Appraiser works statewide because the claims change every few hundred miles. Scroll the regions.
Santa Rosa · Eureka · Ukiah
Wildfire, river flooding, falling redwoods and firs, and FAIR Plan policies on rural homes.
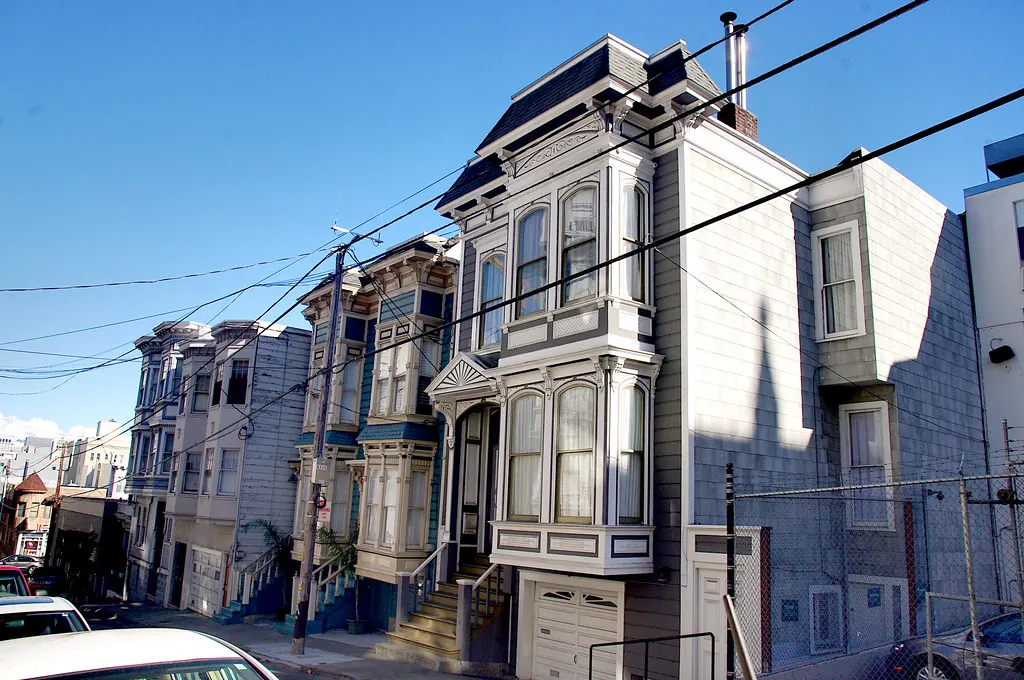
San Francisco · Oakland · San Jose
Shared walls, water between units, hillside fire risk and some of the highest repair costs in the country.
Sacramento · Chico · Redding
Tree impacts in winter storms, atmospheric-river leaks and Camp Fire–scale wildfire exposure in the foothills.
Fresno · Bakersfield · Modesto
Heat-aged roofs, farm buildings, smoke from Sierra fires and snow load at elevation.
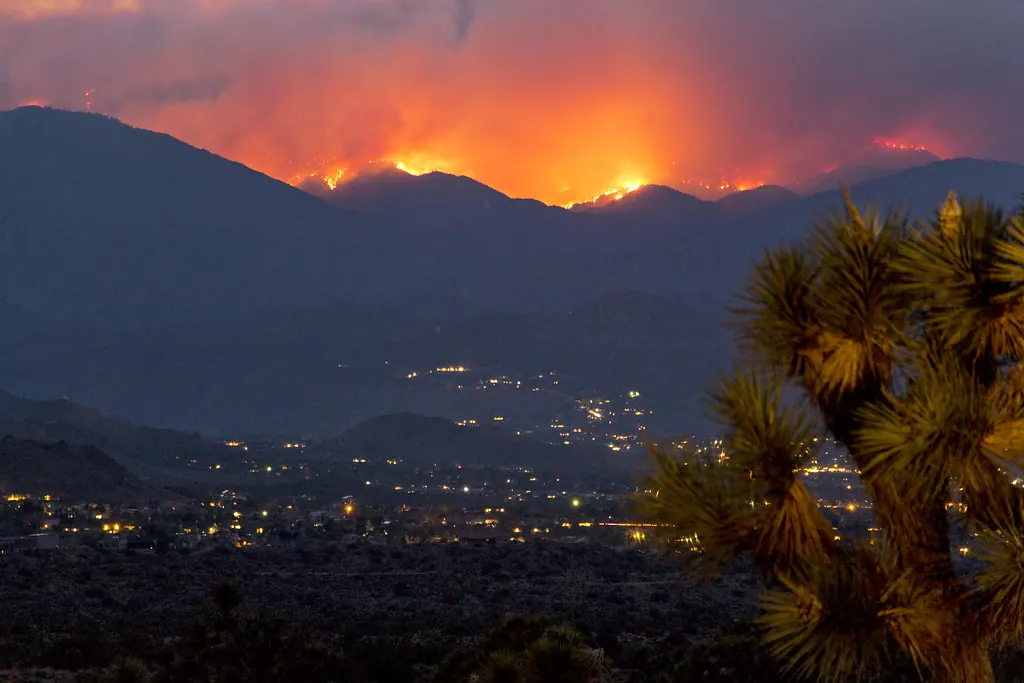
Ventura · Santa Barbara · San Luis Obispo
Canyon wildfires, post-fire debris flows and coastal storms on older homes.
Los Angeles · Orange County · Inland Empire · San Diego
Santa Ana winds, tile roofs, HOA master-policy gaps and the largest wildfire rebuilds in state history.
Free and private
Run the numbers before you call. Every tool works in your browser, and nothing you type is stored or sent.
 Estimator
 Calculator
 Calculator
 Calculator
 Planner
 Checklist
Choosing help
Each solves a different problem. California Insurance Appraiser will point you elsewhere when appraisal isn’t the right tool.
| Question | Appraisal | CDI complaint | Mediation | Attorney |
|---|---|---|---|---|
| Best for | Disputed amount of a covered loss | Claim-handling problems and delays | Negotiated settlement with a neutral | Denials, bad faith, deadlines |
| Result | Itemized award, two of three signatures | Department review of the insurer’s handling | Voluntary agreement, if reached | Settlement or judgment |
| Decides coverage? | No | No | Only by agreement | Argues it in court |
| Typical cost | Own appraiser plus half the umpire | Free to file | Varies; sometimes offered after disasters | Varies by fee agreement |
Where we work most
California Insurance Appraiser works in all 58 counties. These twelve cities have their own pages with local claim history, neighborhoods and housing notes.
All city coverageQuestions
Straight answers about how appraisal works, what it costs and when it’s the wrong move.
We value property damage when you and your insurer agree the loss is covered but disagree on the cost. As your appointed appraiser we inspect, build an independent line-item estimate, work with the carrier’s appraiser and, if needed, present unresolved items to a neutral umpire.
No. A public adjuster manages and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question: the amount of loss. We don’t negotiate outside appraisal and don’t give legal advice.
When coverage is accepted, you have the carrier’s estimate, and the gap between it and your contractor’s number is meaningful, generally more than about 10% or several thousand dollars.
Yes, when the carrier accepts the loss but its rebuild, smoke or contents figure is too low. Appraisal cannot raise policy limits, but it can establish the full cost of the loss.
Each side pays its own appraiser and shares the umpire’s fee. We put our fee in writing before any work starts, and the first conversation is free.
Yes. California Insurance Appraiser works in all 58 counties, from Del Norte to Imperial.
The playbook
Practical guides from California Insurance Appraiser on policy language, documentation and strategy.
 Guide · 7 min
 Guide · 8 minGuide · 6 min
Before you sign a release
A short review now can keep you from accepting a settlement that won’t cover the work.
Start with a conversation
Tell us what happened and what the carrier offered. California Insurance Appraiser will review it and give you a straight answer on whether appraisal is worth pursuing.